
Dangote Refinery Q3 2026 Results: $22.5bn Revenue, $4.7bn Profit, and a Balance Sheet Transformed
By Market Formula Editorial Team / October 2026
Introduction
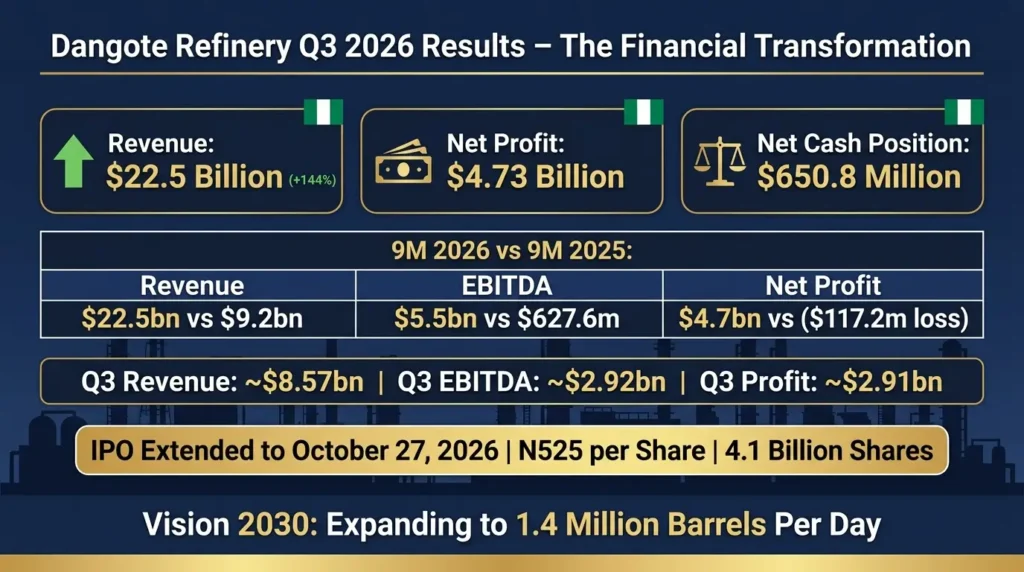
Dangote Petroleum Refinery and Petrochemicals has recorded a remarkable turnaround, posting $22.5 billion in revenue and $4.7 billion in net profit for the nine months ended September 30, 2026. This compares with a loss of $117.2 million in the corresponding period of 2025.
The unaudited financial results, released in Lagos on Tuesday, reveal that revenue surged 144% from $9.2 billion in the first nine months of 2025, while EBITDA jumped nearly ninefold to $5.5 billion from $627.6 million. The performance represents a significant financial milestone for the 700,000 barrels per day refinery, which is currently undertaking a landmark Initial Public Offering (IPO) aimed at broadening African ownership of the industrial complex.
This Dangote Refinery Q3 2026 results analysis breaks down the financial transformation, the third-quarter acceleration, the balance sheet shift from net debt to net cash, and what it all means for investors evaluating the ongoing IPO.
Let’s examine the Dangote Refinery Q3 2026 results with clarity and strategic discipline.
1. The Financial Turnaround at a Glance
The most striking development is the refinery’s transformation from a loss-making operation into a highly profitable enterprise, accompanied by a substantial strengthening of its balance sheet.
9M 2026 vs 9M 2025
| Metric | 9M 2026 | 9M 2025 | Change |
|---|---|---|---|
| Revenue | $22.5 billion | $9.2 billion | +144% |
| Net Profit | $4.73 billion | ($117.2 million loss) | Turnaround |
| EBITDA | $5.5 billion | $627.6 million | ~9× increase |
| EBITDA Margin | 24.56% | 6.83% | +17.7pp |
| Operating Cash Flow | $3.68 billion | $364.7 million | ~10× increase |
| Cash Balances | $6.69 billion | $809.5 million | ~8× increase |
| Net Debt / (Net Cash) | $650.8 million net cash | $1.73 billion net debt | Net cash position |
text
       ┌────────────────────────────────────────────────────────┐
       │   DANGOTE REFINERY Q3 2026 RESULTS – KEY TRANSFORMATION│
       └───────────────────────────┬────────────────────────────┘
                                   │
         ┌─────────────────────────┼─────────────────────────┐
         ▼                         ▼                         ▼
  [ REVENUE ]               [ PROFITABILITY ]          [ BALANCE SHEET ]
  $22.5bn (+144%)           $4.7bn net profit          $651m net cash
  from $9.2bn               vs. $117m loss             vs. $1.73bn net debt
  700,000 bpd               24.56% EBITDA margin       $6.69bn cash reserves
According to the results, net income rose to **$4.73 billion** from a loss of $117.2 million a year earlier, while EBITDA margin expanded to 24.56% from 6.83%, reflecting a marked improvement in the economics of its refining operations. Operating cash flow also increased more than tenfold to $3.68 billion, demonstrating the refinery’s growing capacity to generate cash from its core business.
2. The Third Quarter: Where the Acceleration Happened
The results point to accelerating financial performance during the third quarter of 2026. The refinery didn’t merely improve year-on-year—it accelerated quarter-on-quarter.
Q3 Standalone Performance
| Metric | H1 2026 (6 months) | 9M 2026 (9 months) | Q3 2026 (3 months) |
|---|---|---|---|
| Revenue | $13.91 billion | $22.48 billion | ~$8.57 billion |
| EBITDA | $2.60 billion | $5.52 billion | ~$2.92 billion |
| Net Profit | $1.82 billion | $4.73 billion | ~$2.91 billion |
Revenue increased from $13.91 billion at the end of June to $22.48 billion by September, implying third-quarter revenue of approximately $8.57 billion**-the highest quarterly revenue recorded by the refinery. EBITDA rose from $2.60 billion at the half-year mark to $5.52 billion, indicating the refinery generated approximately **$2.92 billion in EBITDA during Q3 alone.
Net profit also increased from $1.82 billion at the half-year mark to $4.73 billion by September, representing an additional $2.90 billion in the three months to September. Premium Times noted that Q3 alone contributed 61.3% of the entire nine-month post-tax profit, underscoring the pace at which commercial operations have expanded.
3. From Net Debt to Net Cash: The Balance Sheet Story
Perhaps the most significant financial development is the strengthening of the balance sheet. The refinery moved from a net debt position of $1.73 billion in September 2025 to a net cash position of $650.8 million by September 2026.
Why This Matters
The transition to a net cash position indicates that the refinery’s cash holdings now exceed its reported debt obligations on a net basis, a development that strengthens its financial flexibility as it pursues further expansion.
Cash balances climbed to $6.69 billion from $809.5 million, an approximately eightfold increase. This cash buffer provides several strategic advantages:
- Expansion funding – The refinery can finance its $14.3 billion capacity expansion programme without immediate reliance on external debt
- Dividend capacity – Strong cash reserves support the company’s stated intention to declare dividends, potentially in US dollars
- Operational resilience – A robust cash position cushions against commodity price volatility and refinancing risk
It’s important to note that a net cash position does not necessarily mean the refinery has no outstanding loans. It means cash and cash equivalents exceed total debt obligations, which is a materially stronger position than carrying net debt.
4. Management Commentary: What David Bird Said
Managing Director and Chief Executive Officer David Bird attributed the performance to higher throughput, greater operational stability and improved refining margins.
“Our third-quarter performance demonstrates the successful transition from commissioning and ramp-up activities to sustainable commercial operations. Revenue increased to US$22.5 billion from US$9.2 billion in the corresponding period of 2025, while EBITDA rose to US$5.5 billion from US$627.6 million, reflecting higher throughput, improved operational reliability and stronger gross refining margins.”
Bird stated that the results validated the strength of the refinery’s integrated business model and provided a solid foundation for its next phase of growth.
“These results reflect the strength of our integrated business model and provide a solid foundation as we progress through our IPO and execute our Vision 2030 growth strategy. With our expansion programme already underway, we remain focused on increasing refining capacity and broadening our product portfolio. We will continue to strengthen our distribution network across Africa and support energy security across the continent, while creating long-term value for stakeholders.”
5. The IPO Context: Extension and Pan-African Participation
The financial results come at a defining moment for Dangote Petroleum Refinery, whose IPO is seeking to bring a broader cross-section of Africans into the ownership of one of the continent’s most significant industrial investments.
IPO Extension
The company secured approval from the Securities and Exchange Commission to extend the closing date of the offer from October 13 to October 27, 2026, to accommodate growing investor interest across Africa and facilitate wider cross-border participation. The IPO comprises 4.1 billion ordinary shares at N525 per share, representing an offering valued at approximately N2.15 trillion-about $1.6 billion at prevailing exchange rates.
Pan-African Demand
BusinessDay reported that the IPO has drawn subscriptions from over 90 countries, including investors in 51 of Africa’s 54 nations, as the company pitches the deal as the continent’s first truly pan-African share sale.
The refinery said the offer was the biggest ever launched on the Nigerian capital market on its opening day and that it surpassed the previous African record within its first 10 days. Demand has come from retail investors, pension funds, institutional buyers, asset managers and fintech platforms.
What the Results Mean for IPO Investors
The latest financial results provide an important perspective on the IPO proposition, demonstrating the earnings capacity, cash generation and financial strength of the enterprise as it seeks to attract a wider shareholder base. A source close to the refinery’s management said current performance has “progressed significantly beyond the baseline assumptions underpinning the IPO,” suggesting the valuation used in the offer is conservative relative to recent results.
Renaissance Capital has raised its valuation of Dangote Petroleum Refinery and Petrochemicals FZE to N700.41 per share, representing a 33.4% premium to the N525 offer price.
6. Beyond the IPO: The Vision 2030 Growth Strategy
Beyond the immediate IPO, the results also have implications for the Group’s Vision 2030 industrial expansion programme, which includes:
- Increasing refining capacity – from 700,000 bpd to approximately 1.4 million bpd
- Expanding petrochemical production – including polypropylene capacity
- Strengthening distribution networks across African markets
The refinery is currently undertaking a $1.6 billion IPO to help double current capacity from 700,000 barrels per day to 1.4 million by 2030. The strong cash generation demonstrated in the 9M 2026 results provides a solid foundation for this expansion, reducing reliance on external financing and potentially accelerating the timeline.
7. Key Risks and Considerations
While the financial results are objectively strong, investors should maintain perspective.
What to Watch
The Valuation Question
At N525 per share and approximately 124.23 billion post-offer shares, the implied equity value is roughly N65.2 trillion. The strong 9M 2026 results strengthen the earnings case for that valuation, but investors must still ask: how much of this profitability is sustainable across a full commodity cycle?
8. Action Plan for Investors
Step 1: Review the 9M 2026 financials.
The revenue surge, EBITDA expansion, and shift to net cash are objectively strong. Understand what drove them.
Step 2: Assess sustainability.
Refining margins are cyclical. Ask what the refinery can earn in a normalised margin environment.
Step 3: Consider the IPO extension.
The offer now closes on October 27, 2026. If you are participating, ensure your application is submitted before the deadline.
Step 4: Weigh the pan-African demand signal.
Subscriptions from 90 countries suggest broad institutional and retail interest. Demand does not guarantee returns, but it is a useful sentiment indicator.
Step 5: Focus on the long-term thesis.
The Vision 2030 expansion to 1.4 million bpd is the core growth driver. The 9M 2026 results demonstrate execution capability.
Step 6: Apply through approved channels.
Use electronic platforms, SEC-registered stockbrokers, or compliant international platforms.
9. Final Summary & The Bottom Line
The Dangote Refinery Q3 2026 results represent a landmark financial milestone. The company has moved from a $117.2 million loss** to a **$4.73 billion profit in twelve months, with revenue up 144% and the balance sheet shifting from net debt to net cash.
text
  ┌──────────────────────────────────────────────────────────┐
  │   DANGOTE REFINERY Q3 2026 RESULTS – KEY TAKEAWAYS       │
  ├─────────────────────┬────────────────────────────────────┤
  │ Revenue             │ $22.5 billion (+144% YoY)         │
  ├─────────────────────┼────────────────────────────────────┤
  │ Net Profit          │ $4.73 billion (vs. $117.2m loss)  │
  ├─────────────────────┼────────────────────────────────────┤
  │ EBITDA              │ $5.5 billion (margin 24.56%)      │
  ├─────────────────────┼────────────────────────────────────┤
  │ Q3 Standalone       │ ~$8.57bn revenue, ~$2.91bn profit │
  ├─────────────────────┼────────────────────────────────────┤
  │ Balance Sheet       │ $651m net cash (from $1.73bn debt)│
  ├─────────────────────┼────────────────────────────────────┤
  │ Cash Reserves       │ $6.69 billion                     │
  ├─────────────────────┼────────────────────────────────────┤
  │ IPO Closing Date    │ October 27, 2026 (extended)       │
  ├─────────────────────┼────────────────────────────────────┤
  │ Offer Price         │ N525 per share                    │
  └─────────────────────┴────────────────────────────────────┘
The Bottom Line:
The Dangote Refinery Q3 2026 results validate the industrial logic of the project. The refinery is no longer a construction story—it is a cash-generating, profitable industrial enterprise with a strengthened balance sheet.
For investors evaluating the IPO, the results provide a stronger fundamental foundation than the prospectus alone. The company has demonstrated that it can generate substantial revenue, convert that revenue into EBITDA and net profit, and build cash reserves while doing so.
But the investment question remains a valuation question. At N525 per share, investors are paying approximately N65.2 trillion for the equity. The 9M 2026 results make that valuation more defensible than it was six months ago. Whether it is attractive depends on your assessment of sustainable refining margins, expansion execution, and the long-term growth trajectory.
For more weekly NGX updates and strategy guides, explore our market trends and analysis archive.
Disclaimer: This article is for informational purposes only and does not constitute investment advice. The 9M 2026 results are unaudited and have not been independently verified. Always conduct your own research or consult a qualified financial advisor before investing. Past performance does not guarantee future results.